AlgoWay Blog
Guides, manuals and platform references.
Core
- All articles
- FAQ
- PineConnector alternative
- TradersPost alternative
- Automate TradingView alerts
- Automate Telegram signals
- AlgoWay CopyTrader
- cTrader Copier
- TrendSpider with AlgoWay
- How to Automate a TradingView Indicator with Dynamic SL/TP and 1% Risk on MT5
JSON & Alerts
- JSON schema
- Manual alerts
- TradingView without paid subscription
- AlgoWay Strategy Integration in Pine Script
- Python Trading Bot Webhook Integration
- TRALADAL - TradingView Alert Adapter
- TradingView Order Action Alert
MT5 / Expert Advisors
Errors
Integrations
- MetaTrader 5
- TradeLocker
- Match-Trader
- DXtrade
- Capital.Com
- Binance
- Bybit
- MEXC
- OKX
- Bitget
- Hyperliquid
- BingX
- Alpaca
- Interactive Brokers
- Gate.io
- Coinbase
- WEEX
- ProjectX
- cTrader logic
Other Publications
- MT5 EA Webhook JSON Reference
- OANDA MT5 with AlgoWay
- Buy Webhook via Buy Me a Coffee
- AlgoWay vs PineConnector
- Compare AlgoWay with other trading automation tools
- AlgoWay Red News Filter
- Why Paid Trading Indicators Avoid Verifiable Backtests
- How Trade Automation Tools Mislead You
- utomating a Prop-Firm Eval End to End:
- ATP Premium Indicator Testing Bot
- Why TradingView Backtests Win but Live Trades Lose
- Best Prop Firms for Trading Automation and Telegram Signal Copy in 2026
- Four AIs, One Trader, and the Strange Case of TradingView to Alpaca
AlgoWay Strategy Lab
Telegram Copier Duplicate Trades: Causes and Settings
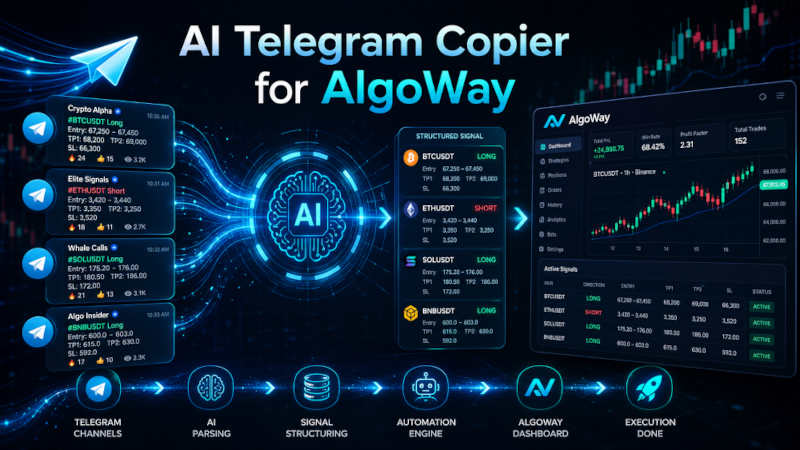
Three trades appear after one Telegram signal. Before deciding that the copier has repeated itself, compare their take-profit levels and add up their sizes. Three small orders with different targets may be exactly what you configured. Three full-size orders deserve a different calculation.
In AlgoWay, multiple take-profit orders and duplicate entry signals are separate cases. Multi Take-Profit Mode controls how one accepted signal becomes orders. Duplicate Protection controls whether another entry for the same symbol is accepted during a chosen period. Switching on the second does not cancel the first.
Verified: September 24, 2026, against the current Telegram Copier settings and execution behavior.
Start with quantity, not the number of tickets
Suppose a signal supplies a total size of 0.30 lots and three valid targets. Assume the destination accepts the resulting lot sizes, with no additional size multiplier. The four AlgoWay choices produce these instructions:
| Multi Take-Profit Mode | Orders requested | Combined requested size |
|---|---|---|
| First TP Only | One order of 0.30 at TP1 | 0.30 lots |
| First 2 TPs | Two orders of 0.15, at TP1 and TP2 | 0.30 lots |
| Split Size Between TPs | Three orders of 0.10, one per target | 0.30 lots |
| Full Size For Each TP | Three orders of 0.30, one per target | 0.90 lots |
Full Size For Each TP multiplies the total requested exposure by the number of targets. It does not divide a single position into smaller portions. With the same stop distance, three full-size entries also carry roughly three times the price risk of one, before execution costs. That is an order-sizing consequence, not a copier malfunction.
Duplicate Protection checks the entry signal before its multiple-target orders are prepared. It therefore allows all the target orders belonging to that accepted signal. Otherwise it would prevent the multi-target feature from doing its job.
These are requested orders, not a promise of matching broker tickets. Quantity minimums, volume steps, fills and account rules still matter. On MT5, a netting account keeps one position per symbol, while a hedging account can hold several. MetaTrader's position-accounting documentation explains that distinction. Inspect the orders, deals and resulting exposure together.
The provider may have sent more than one entry
A channel might publish a short “buy now” instruction, then a fuller entry with a stop and targets a minute later. A human may read those as one developing idea. A copier can receive two actionable entry messages. Similar wording and the same instrument do not automatically turn the later instruction into an update.
Here is an invented timeline showing the difference:
| Time | Detected instruction | With a 30-second protection period |
|---|---|---|
| 12:00:00 | New EURUSD buy passes the other entry checks | The entry is accepted for processing; the protection period begins. |
| 12:00:15 | Another EURUSD entry | Duplicate Protection blocks it. |
| 12:01:00 | Another valid EURUSD entry | The period has expired; the entry may proceed. |
The last entry can proceed even if the first position is still open. A time window is not a position counter. It also is not confirmation that the first broker order filled: the protection check happens before destination execution.
Set the current Duplicate Protection controls
- Open Telegram Copier and use the gear icon for the affected route.
- Enable Duplicate Protection.
- Set Duplicate Protection Duration (seconds). The default is 30; the current field accepts 1 to 86,400 seconds. For example, 300 means five minutes and 3,600 means one hour.
- Save the settings for that route, then test the channel's actual message sequence on a demo destination.
Older instructions describe a fixed 30-second period. The current duration field makes that period configurable. Choose it from the provider's message cadence, not from an assumption that longer is always safer. A five-minute window can suppress a repeated announcement, but it can also suppress a legitimate second entry in those five minutes.
The check is by symbol, not by matching direction or entry price. Another BUY or SELL for that symbol can be blocked during the period, including an opposite-direction entry. Position-management commands such as flat, modify and breakeven are not blocked by this entry check. Other validation and destination rules still apply to them.
Configure each Telegram Copier route deliberately. This control is not an account-wide promise that only one position in an instrument can exist. For connection and the full settings sequence, use the Telegram Copier manual.
A longer timer cannot choose the better signal
If a brief market entry arrives before the complete signal, increasing the duration may preserve the brief entry and block the later, better-specified one. The timer knows which entry arrived first. It does not know which announcement you would have preferred.
When the intended policy is “wait for a signal with protection,” consider SL/TP Requirement: Only With SL & TP. It requires both a stop loss and at least one take profit in the source signal before accepting a new entry. Supplying custom protective distances does not satisfy missing levels in that original signal.
When the intended policy is “accept pending entries only,” Disable Market Entries addresses that different requirement. It blocks market-only entries while allowing valid limit or stop entries with an explicit entry price. It takes priority over Always Market. Neither setting means “wait until the previous position closes,” and neither should be enabled merely to hide an unexplained extra order.
Reconstruct one incident before changing settings
Match the source messages, AlgoWay Webhook Logs and destination history for one short time period. Compare timestamps in the same time zone. Keep this evidence private; a public screenshot does not need your route address or account details.
- One source signal, different targets: compare every order size and target with Multi Take-Profit Mode. Add the quantities before calling the orders duplicates.
- Several source entries: measure their spacing and compare it with the saved protection duration. Include brief market instructions as well as complete signal cards.
- Several routes: check whether two enabled copiers, a clone destination, or another automation source can reach the same trading account. Trace which route produced each order rather than assuming one route's timer coordinates them all.
- An entry apparently repeated after an error: inspect the broker result first. An error row and an open position can coexist; resending without checking can add exposure.
If a BUY appeared during a short exit, the issue may instead be how the exit was expressed. A transaction side alone does not prove whether it opened or reduced exposure. The order-action and partial-exit guide covers that separate problem for TradingView strategies.
A demo test that answers the right questions
Use an isolated test channel and a demo route with a valid small size. Start with First TP Only and a chosen protection duration. Send a valid entry, then a distinctly worded second entry for the same symbol inside the period. Check that the second does not reach execution. Test another valid entry after the period expires, allowing a margin beyond the boundary.
Next, repeat with one signal containing three targets and Split Size Between TPs. Confirm that the requested quantities sum to the intended total, and inspect which orders the destination actually accepted. If you need to test opposite entries or position-management messages, do those separately so their effects remain identifiable.
Keep the resulting rule precise: one accepted signal may intentionally create several target orders; another signal may be blocked for a configured time; an existing position may remain open throughout. Once those three facts are separated, the account history becomes much less mysterious.